Oops! Something went wrong while submitting the form.
Oops! Something went wrong while submitting the form.


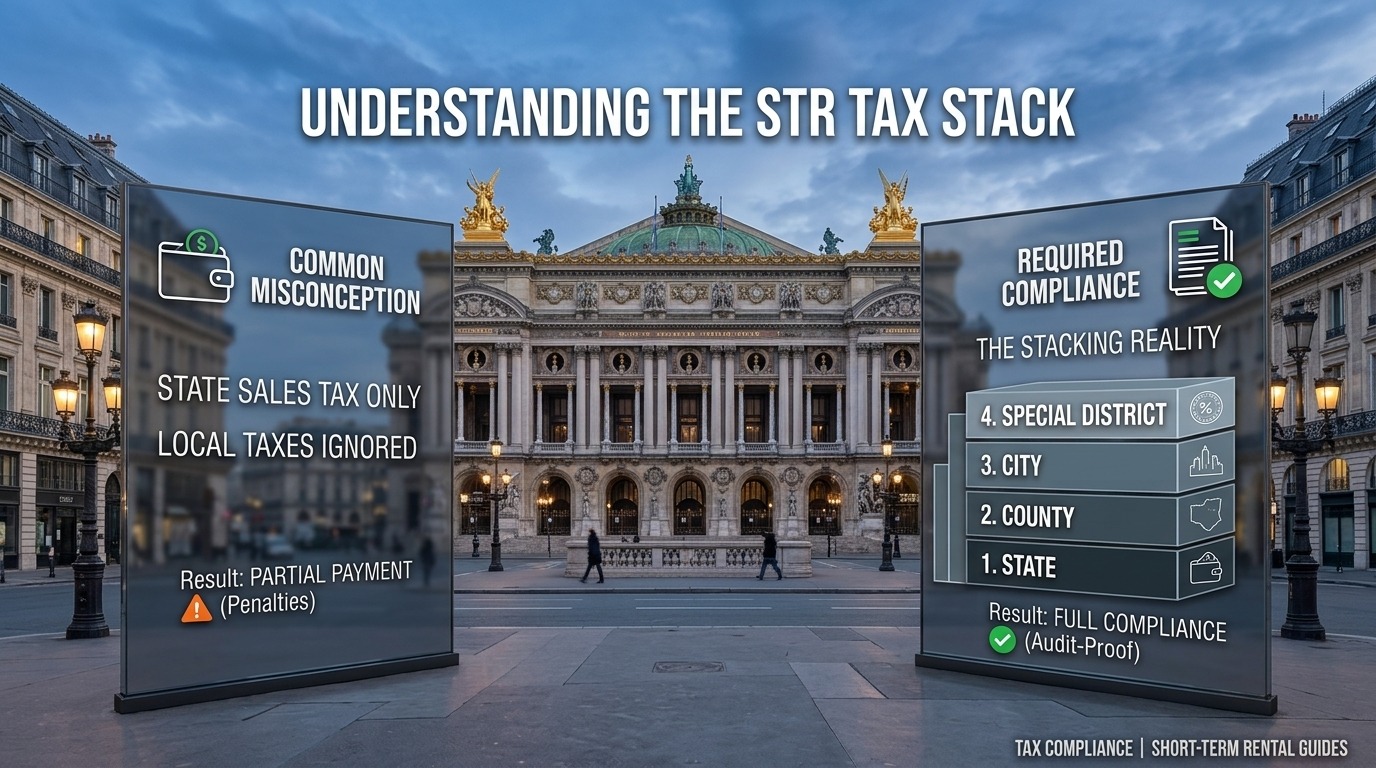
The most common lodging tax mistake among STR hosts is not fraud or negligence. It is architecture. Hosts pay the state, assume they are done, and never see the county or city layer at all. That missing layer is what triggers audits, penalty notices, and compliance gaps that accounting software misses entirely.
The US lodging tax system is not a single tax. It is a structural hierarchy of independently imposed, independently administered, and independently filed taxes that stack on top of a single reservation total. Each layer has its own rate, its own registration, its own return, and its own due date. Paying one does not satisfy any of the others.
Every short-term rental booking in the United States can be subject to up to three distinct tax layers, depending on the jurisdiction.
Layer 1: State sales or transaction tax. This is the foundational layer, collected by the state revenue department. In Florida, it is a 6% state sales tax on all transient rentals of six months or less, administered by the Florida Department of Revenue. In Texas, it is the 6% state Hotel Occupancy Tax, administered by the Texas Comptroller. In New York, it is the state and local sales tax, ranging from 7% to 8.875% depending on the county. Nine states, including Florida, Nevada, Texas, and Washington, charge no state income tax on STR earnings, but all of them still impose transient lodging taxes at this layer.
Layer 2: County lodging surcharge. This is the layer most hosts miss. It sits on top of the state tax, is administered separately, and is often remitted to a different office under a different form number on a different due date. In Florida, this is the Tourist Development Tax (TDT), a county-specific levy ranging from 1% to 6% on top of the state sales tax, bringing Florida's combined burden to 10% to 13% in many markets. Charlotte County imposes a 5% TDT on top of the state's 7% combined rate (state sales tax plus surtax). Seminole County imposes a 5% TDT on top of its 7% combined state rate. Monroe, Orange, Osceola, Palm Beach, and Pinellas Counties are certified for an additional 1% high-tourism surcharge on top of the base TDT.
In Texas, many cities and counties impose a local Hotel Occupancy Tax ranging from 7% to 9%, separate from the state HOT and remitted to local tax offices, not the state comptroller. In New York, the county bed tax and, in New York City, per-unit per-night flat fees represent the second and third layers respectively, bringing NYC's total STR tax burden to approximately 14.75% plus a nightly fee.
Layer 3: Municipal or special district tax. Some cities impose a hotel/motel tax on top of both the state and county layers. Special Tourism Business Improvement Districts (TBIDs) add yet another assessment. In San Diego, the new local rates for 2026 vary by area, ranging from 11.75% to 13.75%, separate from state taxes. Eagle County, Colorado voters approved doubling the county lodging tax from 2% to 4%, effective January 1, 2026. Rhode Island added a new 5% tax on whole-home STRs on top of its local hotel tax increase from 1% to 2%, effective January 1, 2026.
The structural complexity deepens because different layers are administered by different agencies, and even within a single state, counties operate independently of each other.
In Florida, most counties self-administer the TDT, meaning the host registers with and remits directly to the county tax collector's office, not to the Florida Department of Revenue. The state sales tax goes to the state. The TDT goes to the county. These are two separate registrations, two separate returns, and two separate remittance addresses. Some counties, however, do not self-administer and instead have the Florida Department of Revenue collect on their behalf, which means the remittance address is the same but the filing still covers two distinct taxes on one form.
In Louisiana, Act 82 effective January 1, 2026 extended marketplace facilitator responsibility to include local hotel/motel occupancy tax on platform-facilitated bookings, in addition to the state and local sales taxes already required. In Maryland, a new law moves county lodging tax collection through the state Comptroller rather than directly to each county, effective July 1, 2027, giving jurisdictions time to prepare for the new flow.
Illinois added STR properties to the state Hotel Operators' Occupation Tax effective July 1, 2025, creating a new state-level layer that did not previously apply to residential STRs.
Platforms like Airbnb and Vrbo collect and remit some of these layers in some jurisdictions. They do not collect all layers in all jurisdictions, and they never cover direct bookings.
In Florida, Airbnb has a marketplace facilitator agreement covering state sales tax, but TDT collection varies by county. In Santa Rosa County and Flagler County, hosts must register and remit TDT directly regardless of which platform the booking came through. In Seminole County, platforms remit TDT for bookings made through them, but hosts remain responsible for direct bookings.
For portfolio managers running properties across multiple Florida counties, this means the same type of tax, the TDT, is handled by the platform in some counties and directly by the host in others. An accounting system that treats all TDT as platform-remitted will produce compliance gaps in the counties where it is not.
Most accounting platforms used by STR portfolio managers, including property management systems and channel managers, are configured at the property level. The default is often to record what the platform collects without separately tracking what the host owes. That configuration fails when the platform does not collect every applicable layer.
The audit process should answer four questions for every property:
The answers should be recorded at the property address level, not the portfolio level. Tax obligations in Eagle County, Colorado are not the same as obligations in Denver. TDT obligations in Seminole County, Florida are not the same as obligations in Santa Rosa County. Aggregating by state or by platform produces exactly the gaps that county auditors find.