Oops! Something went wrong while submitting the form.
Oops! Something went wrong while submitting the form.


A good CPA can keep your federal return clean, structure your entity correctly, and make sure your deductions hold up under audit. What most general accountants aren't set up to track is a local lodging tax filed with a city or county office that has nothing to do with the IRS, isn't in their tax software, and doesn't show up on any form they normally prepare. That gap is where a lot of STR hosts end up non-compliant without ever being told.
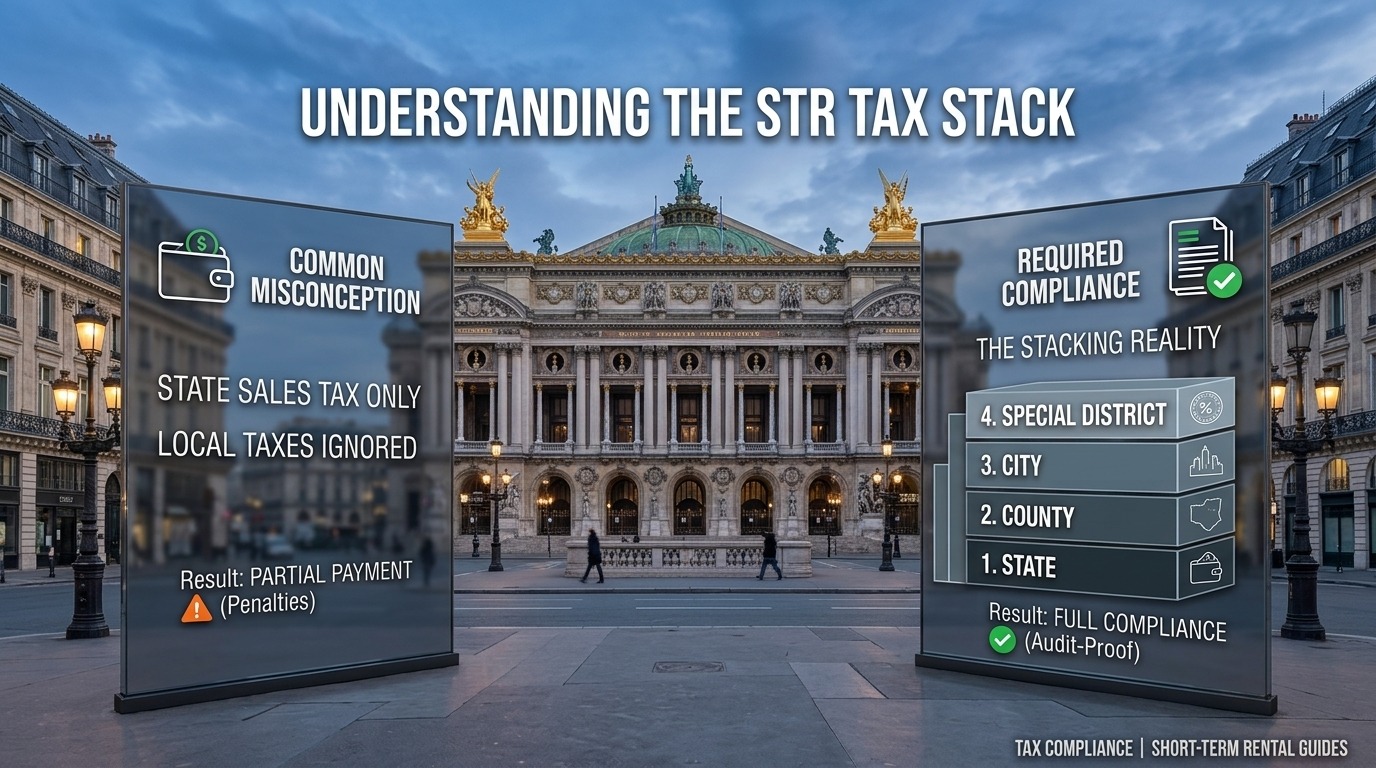
Federal and state income tax and local lodging tax are two entirely different systems, run by different agencies, on different schedules, using different forms, and most general accountants only have visibility into the first one. Lodging tax (also called occupancy tax, tourist tax, or hotel tax depending on where you are) is usually filed directly with a city or county tax office, sometimes through a portal your CPA has never heard of, and it's the host's responsibility to know it exists, not the accountant's.
Standard accounting software and standard CPA training are built around income tax: what you earned, what you can deduct, what you owe the IRS and your state's revenue department. Local lodging tax runs on an entirely separate track, and a few real examples show how easy it is to fall through it.
In the City of Los Angeles, Airbnb automatically collects and remits the 14% Transient Occupancy Tax on bookings made through the platform. That sounds like the tax is handled right? But hosts are still required to hold an active TOT Registration Certificate and continue filing with the city, even when Airbnb is doing the remitting. A CPA reviewing your 1099 or Schedule E has no way of knowing that certificate exists, because it's never touched by anything they normally prepare.
In unincorporated Los Angeles County, there's no ambiguity at all: any rental to a guest staying 30 days or less makes the host liable for TOT, and the county is explicit that not knowing about the requirement doesn't remove the obligation to register and file. This is a county-level tax office, entirely separate from anything your accountant would encounter doing your federal or state return.
San Diego County rolled out a dedicated registration and reporting portal for unincorporated-area hosts in 2024, this is a system built specifically for STR lodging tax, issuing its own registration number, completely outside of any standard bookkeeping or accounting workflow.
And in Texas, hosts can owe Hotel Occupancy Tax at both the state level, filed through the Comptroller's system, and the local level, filed separately with the city, these are two filings, two portals, neither of which shows up automatically in a general accountant's checklist unless they specifically know to look.
None of this is a knock on general accountants. Lodging tax genuinely isn't part of standard CPA training, and most of them are excellent at the job they're actually trained to do. It's just a different job from tracking a county-specific occupancy tax portal.
Here's the part that trips up hosts even when they know a lodging tax program exists: once you're registered, a return is due every period, whether or not you had a single booking. A slow month with $0 in rental income still gets reported, it just gets reported as zero. That's not something a standard income tax workflow ever surfaces, because from a federal or state income perspective, $0 in rental income means there's genuinely nothing to file. Local lodging tax doesn't work that way, and a few jurisdictions make the gap explicit.
Florida: requires a return on both of its tax layers, the state Sales and Use Tax and the county Tourist Development Tax (TDT), so, if for every filing period a host is registered, zero-activity months included. Skip it and Florida Statute 212.12 applies a minimum $50 penalty even on a $0 return, plus 10% of any tax due for every 30-day period the return stays unfiled, up to a 50% cap. Your accountant's software has no reason to flag a return with nothing on it; the county does.
Worcester County, Maryland: (Ocean City) works the same way. Once a host files the initial Application for Room Tax, the county mails a Room Tax Report on a quarterly schedule, although the tax is filled monthly. The county expects one report back every month, occupied or not. A report left unfiled a month past due picks up a 10% penalty on the unpaid tax, plus 0.5% monthly interest starting immediately, accruing on a return that, in a slow month, might otherwise have owed nothing at all. There is also a penalty for not filling the zero return when you have no bookings.
Washington, D.C.: goes a step further and puts the burden on the host explicitly: every operator must register for a business tax account with the Office of Tax and Revenue (Form FR-500), and that requirement stands regardless of whether Airbnb or another platform is already collecting and remitting on their behalf. OTR is clear that hosts remain legally responsible even when a facilitator remits for them. Miss a return and DC applies a 5%-per-month late-filing penalty and a separate 5%-per-month late-payment penalty, both capped at 25%, but both able to apply to the same missed period, plus interest at 10% a year, compounded daily.
A general accountant, working purely from income and expenses, has no natural trigger to file a return reporting nothing. That's precisely why this is a host responsibility, not an accounting one, unless the accountant has been specifically told the lodging tax account exists and needs a filing every period regardless of activity.
Your accountant isn't the wrong person to have, they're just answering a narrower question than the one your STR actually needs answered. Lodge Compliance specializes in exactly the layer general accountants usually miss: identifying every lodging tax jurisdiction tied to your property and keeping those registrations and filings current. Get a free property compliance report at lodgecompliance.com.
A great CPA and a lodging tax gap can absolutely coexist, the fix isn't a new accountant, it's making sure someone is actually watching the layer they were never trained to look at.
Not sure what this means for your property? Get your free compliance report at lodgecompliance.com